




This is a segment from the 0xResearch newsletter. To read full editions, subscribe.
In an open-source industry where applications can and are easily forked, “aggregation theory” — the investor thesis that the winner should build on top of and integrate as many applications as possible — caught on as a promising idea during DeFi summer.
Middleware DeFi aggregators like 1inch, Matcha, Summer.fi (previously Oasis) and Instadapp have all pursued this idea to the fullest, but aggregation theory largely hasnt panned out (Jupiter in Solana world is an exception).
Ethereum DEX aggregators have not outcompeted Uniswap, even though in theory they should.
Instadapp was one such DeFi aggregator that built aggressively on top of blue-chip DeFi protocols like Uniswap, Maker, Aave, Compound and Curve.
After two years in development, Instadapp has reinvented itself. From being the builders of a classic aggregator product, Instadapp has evolved into a platform with a full-fledged DeFi product: Fluid, while the original Instadapp sits separately as a yield aggregator product.
Instadapps pivot has been quite successful: Fluid currently has $1.2 billion in TVL across its money market, while the Fluid DEX on Ethereum is seeing about $428 million in 7-day trading volumes — currently the third-largest DEX behind Curve and Uniswap.
Lets backtrack for a minute. What is Fluid?
The first thing to know is that Fluid is not one app, but a superapp ecosystem. Fluids pooled liquidity layer forms the foundation of the protocol, on top of which sits its own DEX (launched in early November), money market and other vault applications.
Fluid‘s suite of applications borrows aggressively from many of DeFi’s market-tested primitives such as Uni v1‘s auto rebalancing, Uni v3 concentrated liquidity, Aave’s utilization rate curves, Maker vaults debt ceilings and more.
But it also brings to the table a slew of original DeFi innovations — namely more capital-efficient ways of liquidity provision — through its “smart collateral” and “smart debt” features.
For instance, smart debt lets borrowers denominate their debt into trading pairs as liquidity for a Fluid DEX trading pool.
By doing so, traders on Fluid DEX can trade between assets on somebody else‘s debt. From the borrower’s perspective, you can maintain an active loan while simultaneously earning fees from traders to offset your original debt, thereby making debt a productive asset.
In sum, “smart debt” creates liquidity in an entirely opposite direction by which LPs seed liquidity in an AMM pool (i.e., deposit liquidity in two tokens and receive an LP token).
Smart debt has allowed trading pools like USDC-USDT with $20 million of liquidity to emerge on Fluid DEX, while technically being worth $0 in TVL.
“Smart collateral” on the other hand allows LPs to take their LP positions from lending, and rehypothecate them as collateral for AMM liquidity on the Fluid DEX. This allows LPs to earn DEX trading fees on top of lending fees.
This is not technically new — DEXs in the past, such as Cream Finance, have experimented with enabling the use of LP tokens as collateral — but Fluid is managing to execute it more efficiently.
“In Fluid DEX v2, we plan to allow users to select their ranges on both collateral and debt, which will be a breakthrough,” Instadapp chief operating officer DMH told Blockworks.
Fluids governance is governed by the INST token. The token has historically languished as a dead token, until a recent 4x pump in the last month.
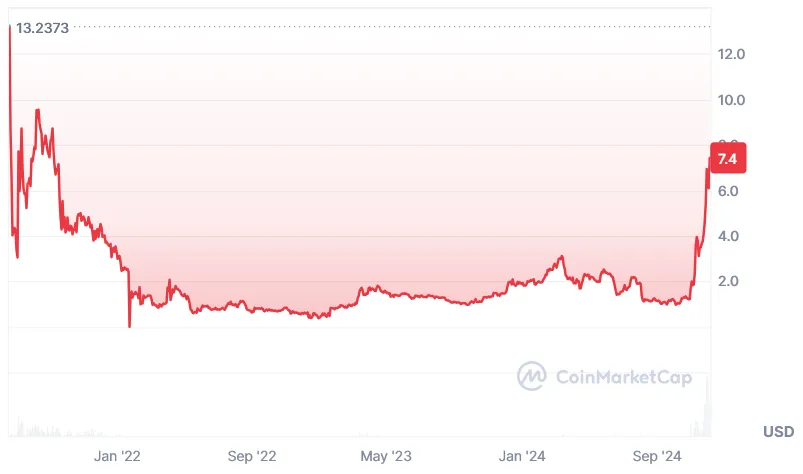
A new governance proposal published yesterday is seeking to convert INST to FLUID at a 1:1 ratio without any dilution or total supply changes.
Upon hitting a target of $10 million in annualized revenues, Fluid will commence a token buyback program to create value accrual for the token.
Finally, the proposal also wants to spend 12% of tokens to fund growth initiatives like pursuing CEX listings, market making and fundraising and seeding an additional 5% of tokens for FLUID liquidity across DEXs.