






According to Christine Lagarde, the head of the European Central Bank, at least 80 central banks around the world are looking at CBDC adoption.
80 Central Banks To Adopt CBDC
“We think that its a duty of us to actually have available digital currencies that would operate to the benefit of consumers,” Lagarde said at a press conference, adding:
“So, what would it look like? Well, it could be used like banknotes. I dont think it is like banknotes, because it will not have the degree of anonymity that banknotes have.”
In talks with consumers who answered in large numbers, Lagarde noted that many remarked, “We want our privacy to be safeguarded, but we dont want anonymity because we realize the risk of anonymity.”
Studies on central bank digital currencies began in China as early as 2014, with Sweden leading the discussion on what an e-krona, e-euro, or e-dollar may look like.
Commercial banks function as safe guardians of deposits may be jeopardized if central banks give access to everyone, with the design now shifting to resemble the present system, in which central banks issue money to commercial banks, who then distribute it to the general public.
The public, like now, would be able to access their digital currency through a bank app, with only banks likely to be able to provide this specific digital currency app, and thus the digital currency itself would remain within the banking system, though some banks may experiment with self-custodian wallets.
For there to be additional public benefits, coders in particular should be able to publish their smart contracts to this bank blockchain, allowing for automated finance and things like NFTs, which would necessitate the creation of a public blockchain, though not one controlled by the public like bitcoin.
All that would be left from a technical standpoint would be privacy concerns, as the central bank and commercial banks would have complete insight into all economic activity. However, such concerns can be addressed by allowing self-custodian wallets to generate their own bank-chain address and connect to the bank-chain network using Simple Payment Verification (SPV) wallets, just as bitcoin does.
The digital bank coins and bitcoin would then compete on monetary merits, with bitcoin having a fixed supply and fiat coins having a controlled quantity.
Except for limited experiments in China, where no self-custodian wallets are allowed for e-yuan, which also lacks publicly publishable smart contracts, digital currencies are still in the early stages, with discussions about their design ongoing.
According to early user feedback, the digital yuans design is similar to that of contemporary digital banknotes, and as a result, it has mostly underwhelmed.
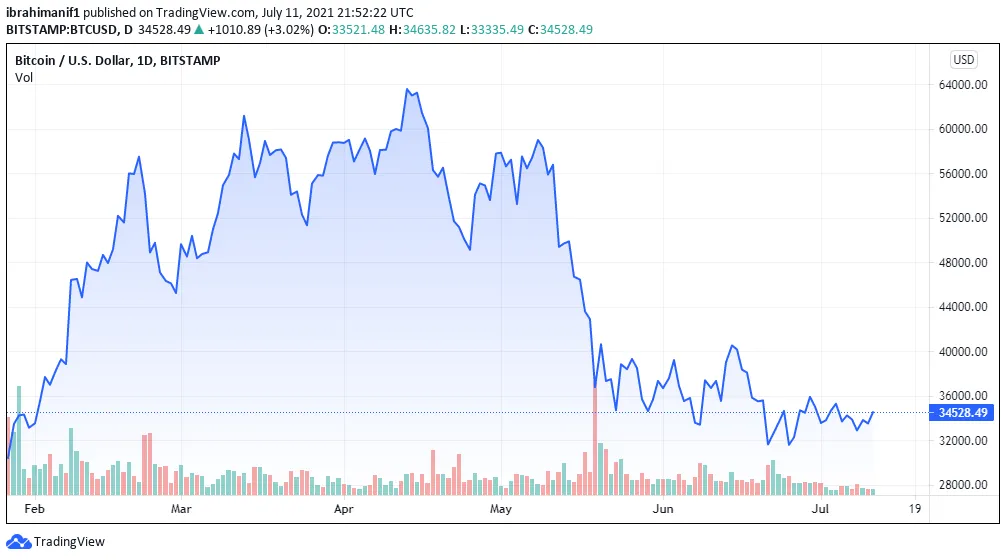
BTC/USD yet to break psychological barrier. Source: TradingView