




A Bank of Canada staff paper found that Aave V3 reported zero non-performing loans in 2024, with overcollateralization and automated liquidations helping prevent lender losses in its Ethereum lending market.
Using transaction-level data from Jan. 27, 2023, to May 6, 2025, the study found that positions were typically liquidated before collateral values fell below outstanding debt, helping contain lender losses across the sample.
But the model came with a tradeoff, the paper said. While it protected lenders from unrecovered losses, it also shifted risk onto borrowers and constrained capital efficiency compared with traditional lending systems.
According to the paper, Aave V3s design relies on automated risk controls rather than traditional underwriting, requiring borrowers to post more collateral than they borrow and liquidating positions when they breach risk thresholds.
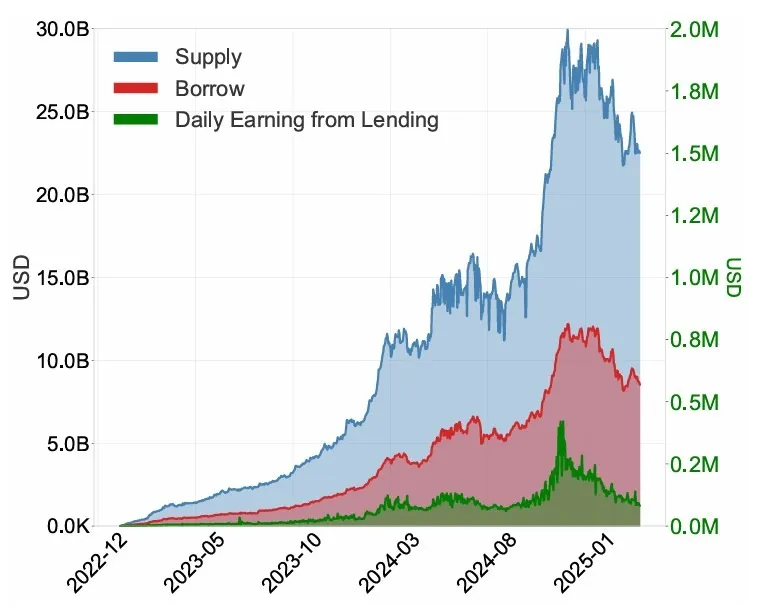
Daily lending earnings, circulating supply, and borrowing volumes (USD) on Aave V3. Source: Bank of CanadaRecursive leverage fueled borrowing demand
According to the paper, Aave V3s lending activity was not driven solely by users seeking liquidity. It found that recursive leverage accounted for over 20% of total borrowed volume and 8.2% of borrowing transactions during the sample period.
Recursive leverage involves repeatedly borrowing against collateral, redeploying the borrowed assets as new collateral and borrowing again to amplify exposure.
Related: Aave V4 goes live on Ethereum after governance vote clears rollout
The study said the dynamic made borrowers more exposed when markets turned. According to the paper, liquidations on Aave V3 tended to occur in concentrated waves, with four assets accounting for 90% of total liquidated value.
This includes Wrapped Ether (WETH), Wrapped Staked Ether (wstETH), Wrapped Bitcoin (WBTC) and Wrapped eETH (weETH).
The paper estimated that borrower losses during major liquidation events could be significant. It said liquidation fees typically ranged from 5% to 10% of liquidated value, while missed gains from subsequent price recoveries pushed combined losses to about 10% to 30% in some cases.
The staff paper suggested that while the design for Aave V3 helped prevent unrecovered bad debt in the sample, it did so by exposing borrowers to abrupt losses when collateral prices fell sharply.